Investment
How to Compare Dubai Property Investment Opportunities
Compare Dubai properties using total cost, realistic operating cash flow, payment timing and exit assumptions instead of relying on headline yield alone.
A useful property comparison makes the assumptions visible. Two opportunities can advertise similar returns while requiring very different amounts of cash, work and patience. Put each option into the same simple worksheet before deciding which one deserves detailed due diligence.
Choose one objective and comparison period
State whether your priority is income, personal use, longer-term value growth or a combination. Pick the period over which you intend to hold the property. A ready rental and an off-plan home scheduled for later completion do not produce the same pattern of cash flows, so a single percentage is unlikely to describe both fairly.
Use the full acquisition cost
Start with the unit-specific price, then add the transaction costs, any financing setup, required works and furnishing relevant to your plan. Show optional upgrades separately. Keep an operating reserve in the worksheet even when it is not a purchase cost; it still affects the amount of cash you need available.
Calculate operating income after costs
Start with a rent estimate supported by relevant comparable properties. Adjust for vacancy and collection risk, then subtract service charges, management, maintenance, insurance and other owner-paid operating costs. Keep the assumptions visible. An estimate for a different building, unit size or letting model is not automatically applicable to your property.
Two useful calculations
- Indicative net operating yield = estimated annual operating income after operating costs ÷ total acquisition cost × 100.
- Indicative cash flow after financing = net operating income − debt payments − other cash outflows not already included.
These calculations answer different questions. The first describes an unlevered operating estimate; the second helps you see the cash you may retain after financing. Neither is a promised return, and tax treatment depends on the owner and the applicable rules. For an off-plan purchase, do not record rental income before the property can actually be occupied and let.
Compare payment timing, not only totals
Lay out the initial payment, subsequent instalments and any large completion balance. A lower total price may require more cash sooner. A longer payment plan may help timing but still involve a substantial commitment. Compare documented offers for the same unit and do not assume that financing or resale proceeds will be available on the date you need them.
Understand off-plan payment plans
Use a consistent decision table
| Factor | What to enter for every property |
|---|---|
| Fit | Target tenant or personal use and location requirements. |
| Acquisition | Price, separate costs and initial cash required. |
| Income | Rent evidence, vacancy allowance and start date. |
| Expenses | Service charges, management, repairs and other owner costs. |
| Funding | Instalments, debt payments and cash reserve. |
| Exit | Holding period, likely buyer and selling costs. |
| Uncertainty | Missing evidence and the assumptions that matter most. |
Run a downside case you can live with
Change the inputs that would hurt your plan: a later handover, a longer vacancy, lower rent, a repair bill or a slower resale. You do not need a complicated forecasting model. The aim is to identify which assumption causes the cash position to become uncomfortable and whether you have a practical response.
Avoid using a future price increase to solve a funding gap today. If the investment depends on selling quickly, include the possibility that it takes longer and that a buyer negotiates the price. Ask what contractual or procedural conditions would apply to a sale at your intended stage.
Match the property to a credible user
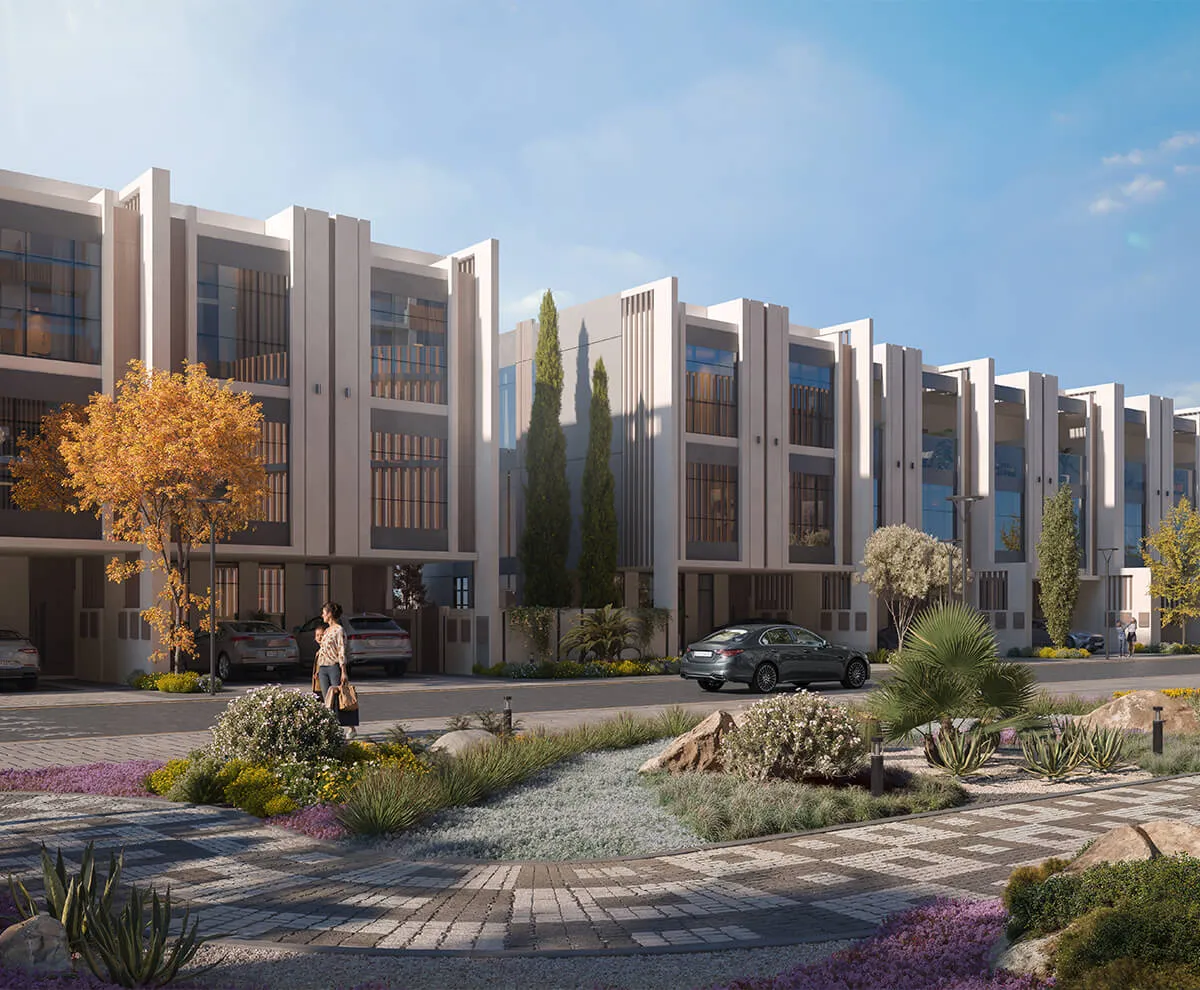
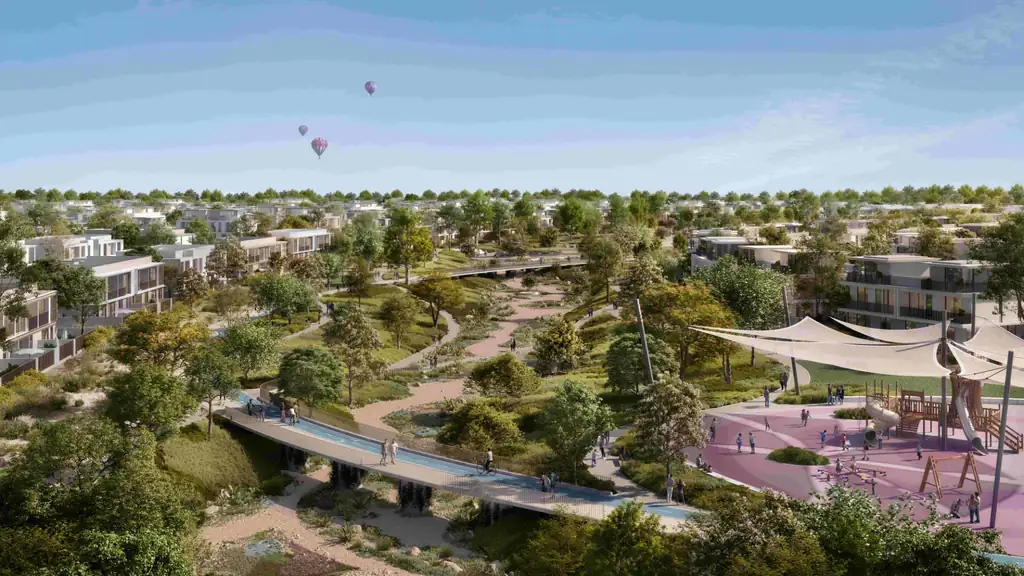
The Valley West appears in the AL SAEB catalogue and is the project illustrated here. For any community, investigate who would actually live there, how they would travel and what competing homes they could choose. A visual impression is useful for discovery; a sound investment case also needs unit-specific costs and evidence of demand.
Explore The Valley West · Compare Dubai properties
Choose the next property to investigate
Rank the options on fit, evidence and affordability under your downside case. Take the strongest candidate into detailed review with AL SAEB, asking for the current quotation, payment schedule and outstanding documents. A good comparison narrows your attention to the questions that can actually change your decision.
Read the international buyer guide · Check the details before purchasing
Frequently asked questions
Should I compare gross yield or net yield?
Understand both, but include operating costs and vacancy when assessing the investment. Use a consistent cost basis and keep financing cash flow separate.
Can an expected future resale price be treated as guaranteed funding?
No. Test whether you can meet the payment schedule if resale takes longer or produces less than expected.